Buying your next home before selling your current one can create a difficult timing issue,…
Home Equity Lines of Credit: How to Upgrade Your Massachusetts Home Without Selling
Upgrading your home can feel out of reach when you’re worried about taking on a new mortgage or draining your savings. **A Home Equity Line of Credit (HELOC) allows you to borrow against the equity in your home, offering flexible access to funds for renovations or improvements, often at lower rates than other types of credit.** In this article, we’ll walk through how HELOCs work, which upgrades qualify, and how Massachusetts homeowners can use this option to revitalize their living space.
Key Takeaways
- Purpose: HELOCs give you revolving access to funds for home renovations, upgrades, or other major expenses.
- Eligibility: You’ll need sufficient equity, a solid credit profile, and the ability to repay.
- Flexibility: Borrow what you need, when you need it—repay and reuse as needed during the draw period.
- Best For: Homeowners in Massachusetts who want to finance improvements without refinancing their first mortgage or selling their property.
Quick Answers: Massachusetts HELOC Essentials
- What is a HELOC? A Home Equity Line of Credit lets you borrow against your home’s equity with a revolving credit line, similar to a credit card.
- Who qualifies? Most lenders require good credit and a history of on-time payments, plus enough equity built up in your existing home.
- When does it make sense? A HELOC can be a solid choice for funding upgrades, repairs, or consolidating higher-cost debt.
- Is my first mortgage affected? Generally, you keep your existing first mortgage as is. The HELOC is a separate, junior lien.
- Are there closing costs? Yes, but they are usually less than a full refinance. Costs may include appraisal, title, and document fees.
Understanding Home Equity Lines of Credit
A HELOC is a revolving line of credit secured by your home. Instead of receiving a lump sum like a home equity loan or cash-out refinance, you can draw funds as needed within your limit during the “draw period”—which typically lasts up to 10 years. Each time you repay a portion, those funds become available again. During this draw phase, you often have the option to pay just the interest or make full payments toward principal and interest.
At Blue Door Mortgage (NMLS# 2218), we see many Massachusetts homeowners leverage HELOCs for everything from kitchen remodels and bathroom updates to new roofs and energy efficiency upgrades. The flexibility this product offers is a major advantage—especially for projects that are completed in stages or when you’re not sure exactly how much you’ll need upfront.
How Does a HELOC Work in Massachusetts?
A HELOC taps into your home’s available equity. Lenders calculate the maximum line based on your property’s appraised value and subtract what you still owe on your first mortgage. While guidelines can vary, most financial institutions in Massachusetts set limits that fall within standard industry ranges.
The process typically starts with a short application and a property valuation—often an appraisal or sometimes an automated value check. Your credit, income, and loan-to-value ratio are all factored into the approval. If you’re eligible and move forward, you’ll get access to your line of credit, which you can use via checks, a debit card, or online transfers.
Common Home Upgrades and Renovations Funded by HELOCs
- Kitchen Remodels
- Bathroom Updates
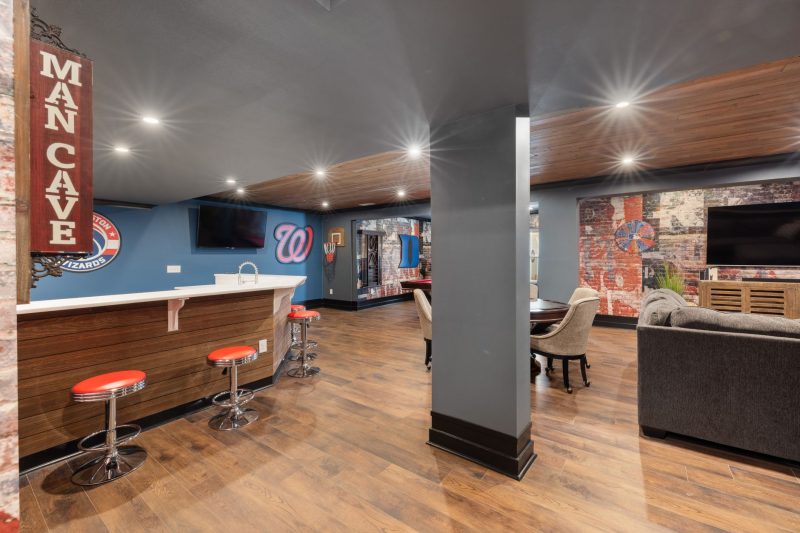
- Finishing Basements or Attics
- New Roofing, Siding, or Windows
- Energy-Efficient Upgrades (solar, insulation, HVAC, etc.)
- Decks, Additions, or Outdoor Renovations
A HELOC offers flexibility for both small and large projects. Not only can you tackle one project at a time, but you have the benefit of keeping funds available for unplanned repairs or future improvements.
Comparing HELOCs to Other Financing Options
| Loan Type | How Funds Are Received | Interest Structure | Best For |
|---|---|---|---|
| HELOC | Revolving line, draw as needed | Variable (often tied to prime rate) | Ongoing or multi-stage projects |
| Home Equity Loan | One lump sum at closing | Fixed | Well-defined, single projects |
| Cash-Out Refinance | Lump sum while refinancing first mortgage | Fixed or Adjustable, based on new first mortgage | Larger renovations, restructuring mortgage |
| Credit Card | Revolving, up to card limit | Variable—often much higher than home-secured options | Small, short-term expenses |
Benefits and Considerations: Is a HELOC Right for You?
- Lower Payment Flexibility: During the initial draw period, minimum payments are often interest-only, helping manage cash flow during renovations or transitions.
- Access Funds as Needed: The ability to draw, repay, and redraw sets HELOCs apart from fixed-term loans.
- May Carry Variable Rates: Interest rates are commonly tied to the prime rate and can change monthly. This could impact total interest paid over time.
- Risk of More Debt: Since your home secures the line, careful planning is key. Avoid the temptation to over-borrow to ensure you can comfortably repay.
- Does Not Change First Mortgage: A distinct advantage if you have a low fixed rate you don’t want to lose by refinancing.
With any financial product, we’re committed to straight answers—HELOCs are a strong tool when used for planned improvements and managed responsibly, but they’re not the right solution for everyone.
Massachusetts HELOC Requirements and What to Expect
- Equity: Most lenders require you to have enough equity available—the difference between your appraised home value and your current mortgage balance.
- Credit: A solid credit profile is usually needed. Higher scores may give you access to larger credit lines or more favorable terms.
- Income and Ability to Repay: Lenders will verify income and debt payments to ensure you can afford the potential new payment.
- Closing Process: Generally streamlined, requiring less documentation than a full refinance. Allow time for appraisal and underwriting, but timelines are often shorter than primary mortgages.
Every scenario is unique. If you’re self-employed, a first-time user of home equity financing, or considering a move-up renovation, we’re here to guide you through all requirements with professionalism and clarity.
Getting Started: Is a HELOC Right for Your Upgrade?
Consider your project scope—will your spending be spread out over time? Are you satisfied with your current mortgage rate and terms? Do you want a safety net for future unexpected repairs? If you answered yes to any of these, a HELOC may be worth a closer look.
At Blue Door Mortgage, our experienced team is available to walk you through your options, review the numbers, and explain how a HELOC stacks up against other financing paths given your specific scenario.
Steps to Apply for a HELOC in Massachusetts
- Evaluate Your Goals: Identify your project needs and budget range.
- Check Your Equity: Review your mortgage statement and get a sense of your current home value (many lenders offer online estimators).
- Connect with a Mortgage Professional: Discuss your goals and review eligibility, rates, and how a HELOC could fit your situation.
- Complete Application and Documentation: Submit income, asset, and property information for underwriting review.
- Review Closing Disclosures: Understand the costs, payment structure, and how to access your line after closing.
Ready to Explore Your Options?
A Home Equity Line of Credit can give you the flexibility to make meaningful improvements to your Massachusetts home without sacrificing a great first mortgage or draining savings. The first step is understanding your equity position and what fits best for your plans.
If you’re thinking about a renovation or want to compare how a HELOC works alongside other home financing options, please reach out. Call, text, or email us at your convenience—our Blue Door Mortgage team will review your scenario, answer questions, and help you understand your next steps, including pre-approval planning when the time is right.
Frequently Asked Questions
How is my HELOC limit determined?
Your HELOC credit limit is based on your current home value minus your existing mortgage balance, subject to individual lender guidelines and Massachusetts regulations. Each lender may offer different percentages or maximum amounts.
Does a HELOC change my first mortgage or rate?
No, a HELOC is typically a second mortgage and does not affect your existing first mortgage's rate, payment, or terms. It's a separate line of credit secured by your home.
Are HELOC interest rates fixed or variable?
HELOCs commonly have variable interest rates that may change periodically based on the prime rate or another index. Some lenders offer fixed-rate conversion options on draws, but this varies by program.
How do I access funds from my HELOC?
Most HELOCs let you access funds via checks, debit cards, online transfers, or in-branch withdrawals. You can draw as needed up to your approved limit during the set draw period.
What are the typical closing costs for a HELOC?
Closing costs for HELOCs in Massachusetts usually include appraisal, title, and document fees. These are often lower than a full refinance, but costs vary by lender; always review your disclosures carefully.
This is educational and not financial advice. Loan programs and guidelines can change. Talk with a licensed mortgage professional about your specific scenario.

About the Author
Jonathan White
President at Blue Door Mortgage · NMLS #3443
I am the President and one of the producing Mortgage Brokers for Blue Door Mortgage located in Brookline, Massachusetts. With over 29 years in the Mortgage Brokerage business, I have helped thousands of homeowners and generations of their families with the purchasing and refinancing of their properties.
Specializes in: Conventional, FHA, Jumbo
Licensed in: FL, MA, NH, RI
Related Posts